Builder 100 Trends Show a Market Built for Sellers
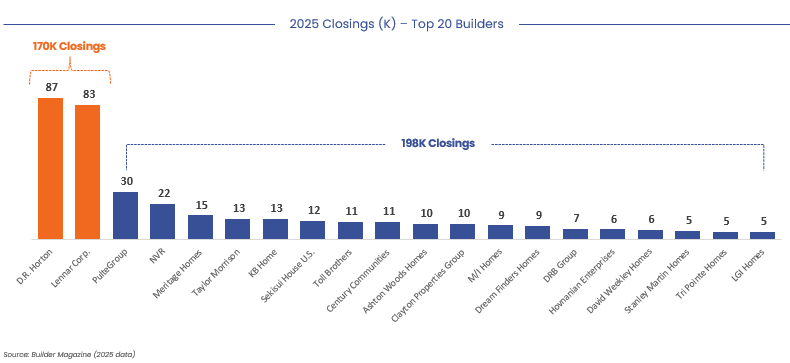
We are always fascinated by the trends that surface in Zonda’s annual Builder 100 and Local Leaders data around market share, growth strategies, geographic performance, and consolidation. The M&A markets remain white-hot, with valuations indicating that it’s still a sellers’ market. Please contact us to discuss your M&A strategy.
Horton and Lennar Continue Dominance, but Via Opposite Playbooks
Together, they closed 170K homes in 2025 with 43K, or +35%, more than the next eight builders combined, up from a 30% gap in 2024
They got there differently: Horton pulled back (units -7%, revenue -9%); Lennar bought share through pricing (units +3% on revenue -5%)
Publics Control the Top Position in 44 of 50 Markets
Horton and Lennar hold the #1 spot in 37 markets (versus 38 in 2024). Lennar now leads 25 markets (up from 21); Horton leads 12 (down from 17)
The average #1 builder holds a 23.5% market share (median ~22%), and 17 markets have a leader above 25%
Lennar is the standout with 30+% share in six markets
The Top 50 Markets Cooled in 2025
The largest 50 MSAs closed ~402K new homes, down from ~426K in 2024. That is ~59% of national closings, down from ~62% in 2024
Only 10 markets delivered more than 10K closings, down from 14 in 2024, while just 11 builders delivered more than 10K closings
Texas Does More with Less
Once again, Florida had the most markets (12) ranked among the top 50 MSAs, ahead of South Carolina (5), Texas (4), and North Carolina (4)
Texas’ four markets produced ~111K closings, which is ~28% of all top 50 MSA volume, versus Florida's ~77K
Consolidation Continues
There have been 39 private and six public homebuilders acquired by 31 different buyers since the beginning of 2024
Diversified and overseas parent companies keep climbing the rankings through acquisition: Berkshire Hathaway (Taylor Morrison + Clayton Properties subsidiaries), when consolidated, would rank as the #4 builder at 27K closings
The Japanese housing companies represent nearly 37K closings, up from 35K in 2024
If consolidated, Sumitomo’s subsidiaries would account for the #6 largest builder with ~15K closings; Daiwa House would be #13 at ~9K closings. Sekisui House currently reports on a consolidated basis and sits at #9 with ~12K closings
A Frozen Top, a Churning Bottom
The top 25 shifted an average of ~2 spots between 2023 and 2025
Below them, constant turnover: 54 new builders have entered the Builder 200 between 2023 and 2025
The fall conference season is already underway, and our team will be attending many industry events. If you plan to be in attendance, please reach out to coordinate time to discuss your company’s growth strategy and capital needs, and to exchange notes on the evolving market landscape.